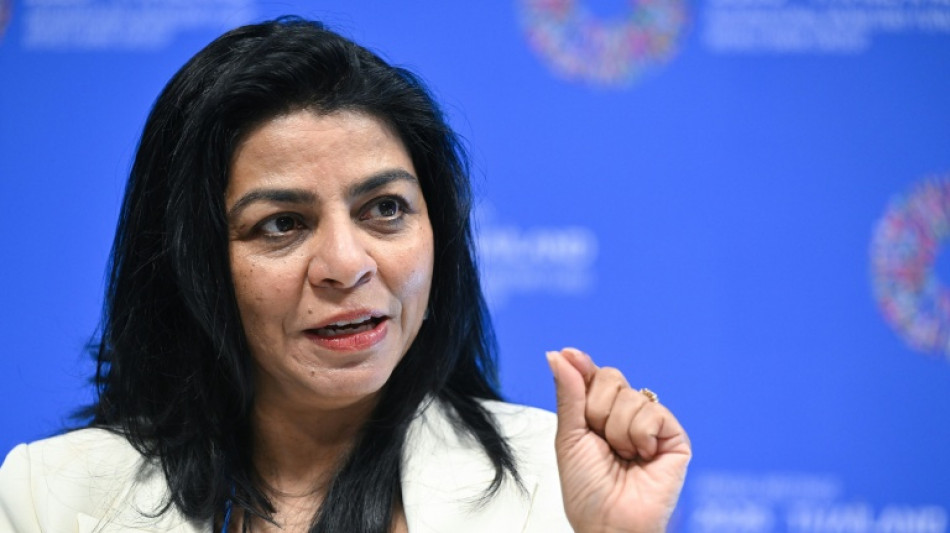
Advanced economies must 'act now' to lower debt as bond yields spike: IMF / Photo: Panumas Sanguanwong - AFP
The International Monetary Fund on Wednesday called for advanced economies to "act now" to address ballooning debt, with spiking bond yields at multi-decade highs and pressure growing on central banks to hike interest rates.
Global public debt is at its highest level since the Second World War and on track to soon exceed 100 percent of global gross domestic product, and the Fund lamented the lack of any major progress in reversing the trend.
"The fundamental message (is) that countries need to act now, particularly if you have high levels of debt, in order to create that room for higher spending pressures," said Era Dabla-Norris, the Fund's deputy director at the Fiscal Affairs department, referring to spending on defence, ageing populations and other priorities.
While rises in debt have been broad-based, advanced economies have seen their debt-to-GDP ratios skyrocket since the global financial crisis in 2008, the pandemic and the wars in Ukraine and Iran, as they increased spending to deal with the series of economic shocks.
Since late February, yields have increased by an average of around 110 basis points, especially on longer maturities, Dabla-Norris told AFP on the sidelines of the IMF's Annual Meetings in Bangkok.
On Tuesday, US 10- and 30-year Treasuries were trading at their highest yields since around 2002, with other G7 bonds following similar trajectories.
The spike has been driven by a combination of factors, including heightened inflation expectations caused by skyrocketing energy prices caused by the Iran war.
That, in turn, has caused many central banks to step in to address price stability, with authorities hiking borrowing costs to curb prices.
The rise in rates has contributed to increases in bond yields on the short end of the curve, which has been seeing issuances in greater numbers, Dabla-Norris said.
"High debt and shorter maturities definitely makes the interaction between fiscal and monetary policy more complex than it did in the past," she said.
"What that really means is that if short-term interest rates change -- so say monetary policy tightens -- that can quickly spill over into government borrowing costs much faster than if the maturity structure was longer."
- Communication is key -
In that situation, existing high debt levels act as an "amplification mechanism" for the effect on yields.
Worldwide, governments' average interest payments are projected to rise from 2.3 percent in 2021 to 3.7 percent in 2031, research released by the IMF on Wednesday showed.
In the United States, interest payments are projected to climb from about 2.8 percent of GDP before the pandemic to 5.7 percent in 2031, or "roughly equal to projected expenditure on Social Security," the report said.
In low-income countries, the situation is even more dire, with interest payments taking an average of 15 percent of tax revenues.
The solution, the IMF says, is that governments need to undertake fiscal consolidation now.
"Countries will now have to increase primary balances much more than they did in the recent past in order just to stabilise debt ratios," said Dabla-Norris.
She warned that higher benchmark yields in advanced economies could also spill over to emerging markets by tightening global financial conditions.
Dabla-Norris said governments needed to communicate clearly why consolidation -- which can mean painful spending cuts -- needs to happen.
"What's important beyond just having the right credible strategies in order to bring that down is to be communicating what the trade-offs are to the public.
"I think this is really absolutely crucial because the trade-offs mean that the governments have much less room for manoeuvre within budgets," she said.
"By not starting on the consolidation path today, you're just kicking the can down the road."
O.Zimmermann--HHA